Start a conversationLet’s talk

Don’t run from a conversation.

It’s better to talk to a professional when it comes to making the best decision with your money.

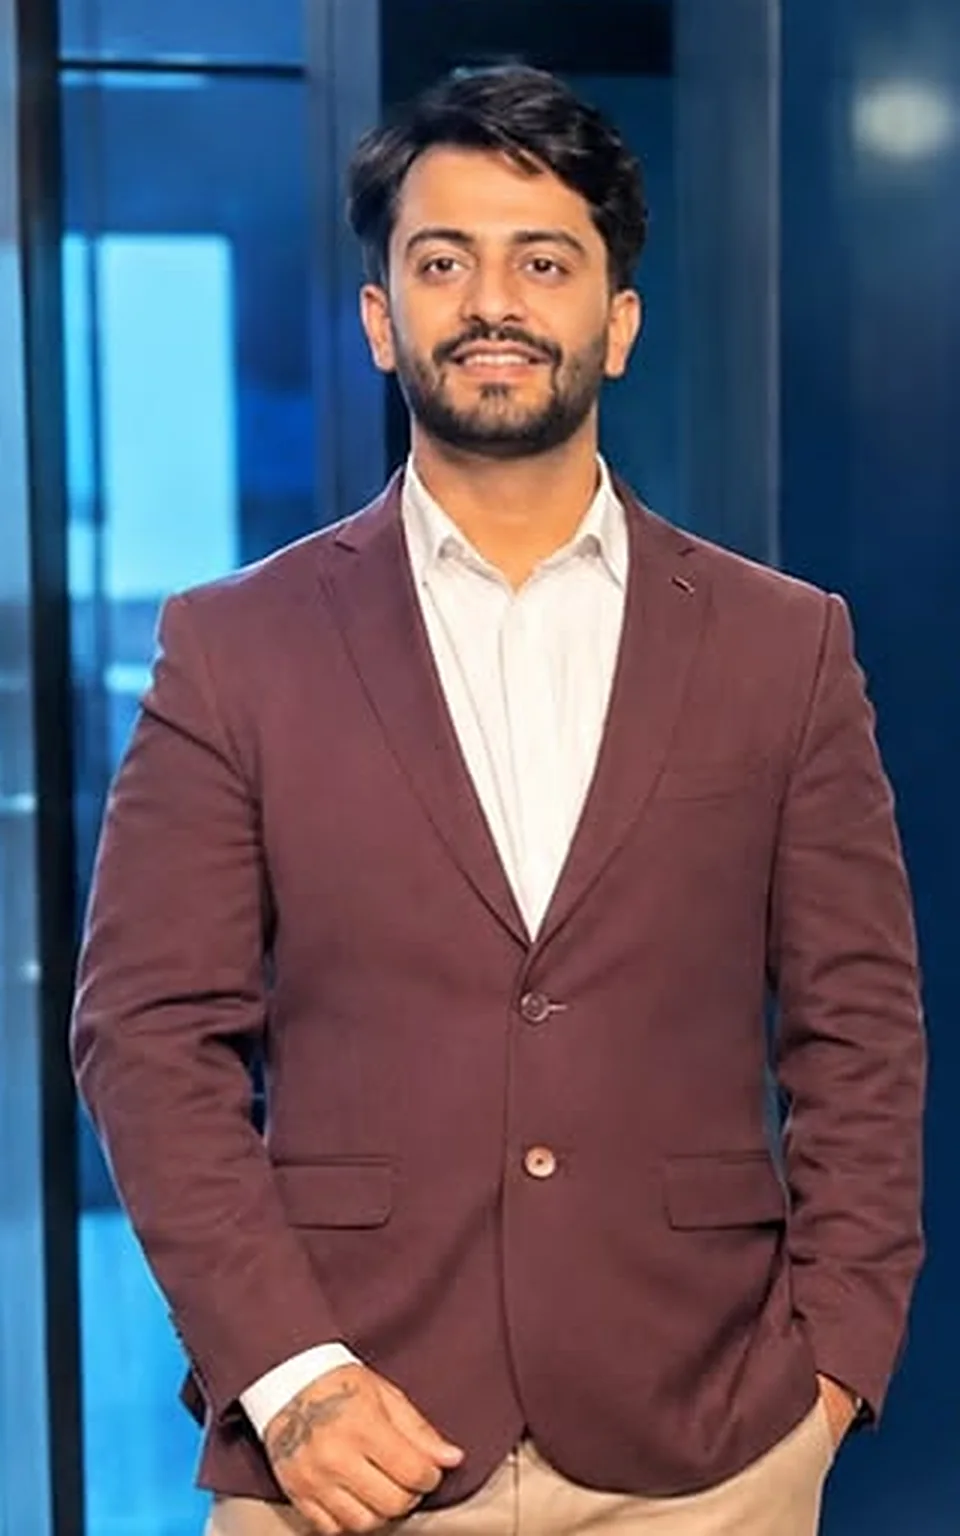
Tanuj Chopra, Financial Advisor
Let me be your Finance Guy.Tanuj Chopra, Financial Advisor

The conversations people keep putting off.

The right insurance helps protect your income, family and long-term plans from life’s uncertainties. Here is where most of these talks begin.

If something happened to me, would my family be okay?
Life insurance

Most people don’t know the real answer until they sit down and do the math. Life insurance pays a lump sum to the people you name, generally tax-free, so the mortgage, the debts and the everyday bills don’t become their problem.

What we’d go through together

  • What your family would need, and for how long
  • Term or permanent coverage, and what each one costs you
  • What you already have through work
Talk to me about this

What happens to our plans if I get seriously sick?

Critical illness insurance

Provincial health care covers much of your treatment. It doesn’t pay your mortgage while you recover. Critical illness insurance pays a lump sum if you’re diagnosed with a condition your policy covers, and you decide how to use it.

What we’d go through together

  • Which conditions a policy covers, because it varies
  • How much coverage makes sense for your household
  • How it fits with any benefits you already have
Talk to me about this

What if I couldn’t work for six months?

Disability insurance

Your income pays for everything else, and it’s easy to forget it can stop. Disability insurance replaces part of your income if an illness or injury keeps you from working.

What we’d go through together

  • The waiting period, and how long benefits last
  • How the policy defines “disability”
  • What your group plan really covers, or what to do if you’re self-employed
Talk to me about this

TFSA, RRSP or RESP. Which one do I actually need?

Investments

Possibly more than one. They do different jobs.

TFSA
Growth and withdrawals are tax-free. Useful for almost any goal.
RRSP
Contributions can lower your taxable income now. Withdrawals are taxed later, usually in retirement.
RESP
Saves for a child’s education. The Canada Education Savings Grant adds 20% on the first $2,500 you contribute each year, up to $500 a year and $7,200 per child over their lifetime.

What we’d go through together

  • What you’re saving for, and when you’ll need it
  • How much risk you’re comfortable with
  • Which account to fill first

Investments can go down as well as up.

Talk to me about this

When can I actually stop working?

Retirement planning

It depends on what you want that life to look like and what you’ll have coming in. A retirement plan turns a vague hope into numbers you can work with.

What we’d go through together

  • The age you’re aiming for, and what you’ll spend
  • What CPP, OAS and any workplace pension may provide
  • What your savings need to do, and the order to draw on them
Talk to me about this

I don’t even know where to start.

That’s exactly when to talk. Tell me what’s on your mind and we’ll work out the rest together.

Start here

How the conversation goes.

  1. You tell me what’s on your mind

    A worry, a goal, or a policy you’ve never really understood. Any of it is a good place to begin.

  2. We look at the whole picture

    Your income, your family, your debts, and what you already have in place.

  3. You get a plan that fits

    One built around your goals and what matters most to you, explained in plain language.

Before you reach out.

What should I have ready before we talk?

Nothing has to be perfect. A rough idea of your income and debts helps, along with any insurance policies or investment statements you already have. If you can’t find them, we can still start.

I already have insurance through work. Do I still need to talk?

It’s worth checking. Group coverage is often tied to your job and can end when you leave, and the amount may not match what your family would need. We can look at what you have and see whether there’s a gap.

Am I too young, or have I left it too late?

Neither. Starting early gives your money more time, and starting later just means the plan has to fit the time you have. Either way, the first step is knowing where you stand.

Do I have to decide anything during the conversation?

No. The point of talking is to understand your options. Take the time you need before you make a decision.

Let’s talk about a plan that fits your goals and protects what matters most.

Send me a message and I’ll get back to you.

Please don’t include your SIN, account numbers or health details here.